Insurance That Works The Way You Do
From embedded experiences to traditional programs, our insurance can be built around your business.
The right insurance can make a real impact on your operations - and your customers'.
Less risk for you. Less downtime for them.
 Why You'll Love It
- Faster closings from less insurance friction
- New revenue opportunities
- Increased customer satisfaction and retention
 Why They'll Love It
- Broader coverage than other commercial policies
- Fixed pricing with easy repair or replacememt
- Claims professionals who know equipment
Protecting Equipment Across The U.S. and Canada
Physical Damage Insurance
Covers most types of physical loss or damage, including risks that are often excluded from standard policies (like flood, wind or transit).
Stipulated Loss Gap Coverage
Insures the difference between the actual cash value of commercial equipment and the unpaid balance on the lease in the event of a total loss.
Equipment Residual Value Insurance
Allows lessors to account for operating leases like finance leases - accelerating earnings and protecting against unforeseen declines in market value down the road.
Insurance Tracking
Monitors coverage status and detects uninsured assets that create risk for your business. Included in embedded insurance programs or available as a stand-alone service.
Rental Loss Damage Waiver
Provides coverage for equipment while out on rental.
Machine Tool Operator Error
Covers physical damage to a machine tool caused by an operator's programming.
Contingent & Excess Liability
Protects against legal exposure in a lawsuit involving a lessor's equipment.
Repossession
Protects a lessor during the repossession process of equipment or commercial titled vehicles.
Equipment Types
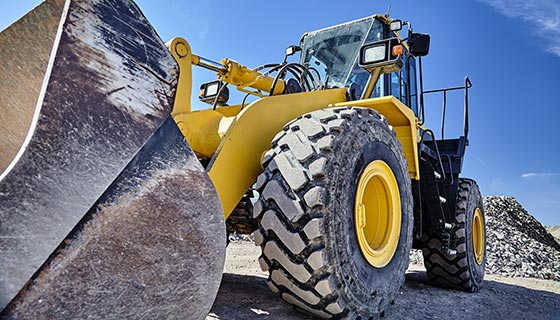
Construction & Earthmoving Equipment
- Backhoes
- Drilling Equipment
- Excavators
- Graders and Loaders
- Skid Steers
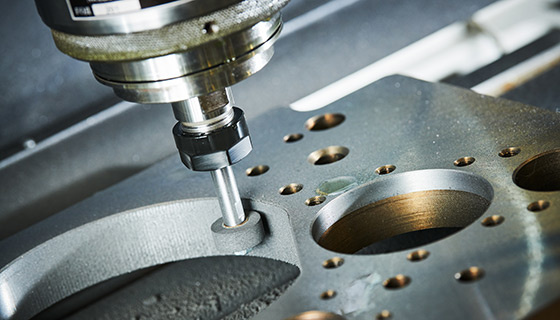
Industrial & Manufacturing Equipment
- 3D Printers
- Automotive and Garage Equipment
- Embroidery Equipment
- Machine Tools, including CNC
- Material Handling Equipment
Medical & Healthcare Equipment
- Dental Equipment
- Digital Radiography and Scopes
- Healthcare Equipment
- Mobile Medical Equipment
- Veterinary Equipment
Office & Business Equipment
- Copiers and Printers
- Mailing Equipment
- Phone Systems
- Printing and Binding Equipment
Outdoor, Recreation & Landscaping Equipment
- Amusement Equipment
- Chippers and Stump Grinders
- Golf Carts
- Lawncare Equipment
Retail, Hospitality & Commercial Equipment
- Fitness Equipment
- Laundry Equipment
- Registers, Scanners, and Point of Sale Systems
- Restaurant and Vending Equipment
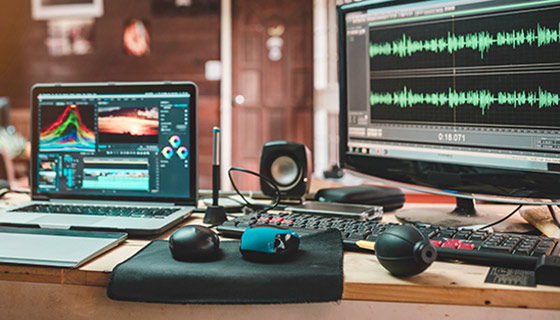
Technology, Media & Security Equipment
- Broadcasting Equipment
- Computers and Servers
- Photography and Videography Equipment
- Recording Equipment
- Security Systems
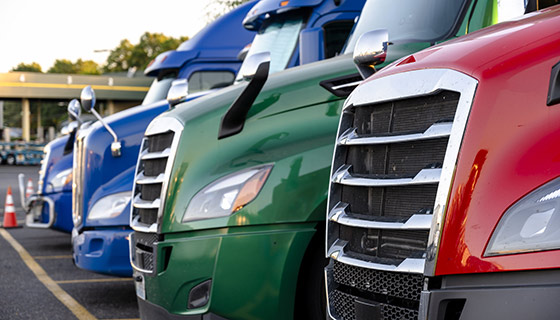
Transportation & Mobile Assets
- Commercial-Titled Vehicles
- Trailers
- Railcars
- Barges
Not sure what's right for your business?
Every business is different, so we tailor insurance solutions to fit your needs. Let's connect for a quick 30-minute conversation and identify the best path forward.
What clients are saying
"Our insurance program has been a game-changer for our business operations. The program helps accelerate our customers’ transactions. This enhancement in speed and service has not only improved customer satisfaction but has also reinforced our clients' trust in us."
– Lyndon Thompson, President of Byline Financial Group
"Great American specializes in insuring equipment finance risks. They tailor programs to meet clients’ needs and recommend solutions to enhance the customer experience through deep, customer-focused interactions."
– Shaun Buswell, Vice President with Alliance Funding Group
"The digital solutions we implemented with Great American will enhance customer experience, operations and communications. We look forward to future opportunities to support our customers together."
– Daryn Lecy, CLFP, Senior Vice President and COO with Oakmont Capital Services
Specialty Equipment News
2026 Hurricane Season Forecast Calls for Below-Normal Activity—Preparedness Still Key
The National Oceanic and Atmospheric Administration (NOAA) is predicting a below-normal Atlantic hurricane season for 2026, marking a shift from the elevated activity seen in recent years. According to NOAA’s outlook, there is a 55% chance of a below-normal season, with only a 10% chance of above-normal activity.
Forecasters expect between 8–14 named storms this year, including 3–6 hurricanes and 1–3 major hurricanes. For context, a typical season averages 14 named storms, 7 hurricanes, and 3 major hurricanes. [noaa.gov]
A key driver behind the quieter outlook is the anticipated development of El Niño conditions. El Niño tends to increase wind shear in the Atlantic, which can limit storm formation and intensity.
While this year’s prediction points to less activity overall, experts caution against complacency. Seasonal forecasts do not predict where storms will form, or whether they will make landfall, and it only takes one storm to create significant disruption. [cpc.ncep.noaa.gov]
Staying prepared and aware may help you proactively plan for potential exposures as the hurricane season unfolds. Here are some preparation considerations.
What to Do Before the Storm?
Tropical cyclones present several threats. Strong winds being the primary one typically associated with storms, water hazards including storm surge and heavy rainfall present greater hazards. Here are some practical tips you could implement to maximize damage prevention for your property:
- Pre-inspection: Complete a thorough documented inspection of your property to identify potential problems. Do this before a hurricane watch (36 hours in advance) or warning (24 hours) is issued.
- Consider hiring an architectural or engineering professional certified by a state or municipal retrofit program.
- Window protection: Install storm shutters, or board up windows using five-eighths inch marine plywood cut to fit. Avoid using tape, as it does not prevent breakage.
- Seal openings: Cover exterior openings such as vents and outdoor electrical outlets using urethane-based caulk to prevent water intrusion.
- Strengthen doors: Install hurricane-proof doors with at least three hinges and a one-inch long dead bolt lock. Use temper glass for sliding doors and protect them like windows. Reinforce garage doors with wind- and impact-rated systems.
- Reinforce roofing: Use straps or hurricane clips to secure roof connections. For gable-end roofs, add bracing to increase wind resistance.
- Landscaping: Remove weak trees, trim branches and shrubbery, and replace gravel with fire-resistant materials.
- Secure outdoor property: Move boats and trailers to safe and secure locations. Bring smaller items indoors. Secure fencing and mailboxes to the ground is possible.
Additional Hurricane Safety Tips
- Emergency plan: Consider drafting a comprehensive formal written plan that addresses all efforts to be taken during and after a tropical storm. This will help to ensure that all possible measures are being considered and implemented to prevent and mitigate damage. It can be easy to overlook a simple measure in the chaos and aftermath of a tropical storm.
- Stay informed: Take time to learn about your property, including elevation and if it is located in a flood zone or in an area prone to flooding. Identify nearby bodies of water as well as levees, dams, etc. Ensure information is being gathered from official sources that are qualified to provide reliable information.
- Property & Casualty
- Specialty Equipment